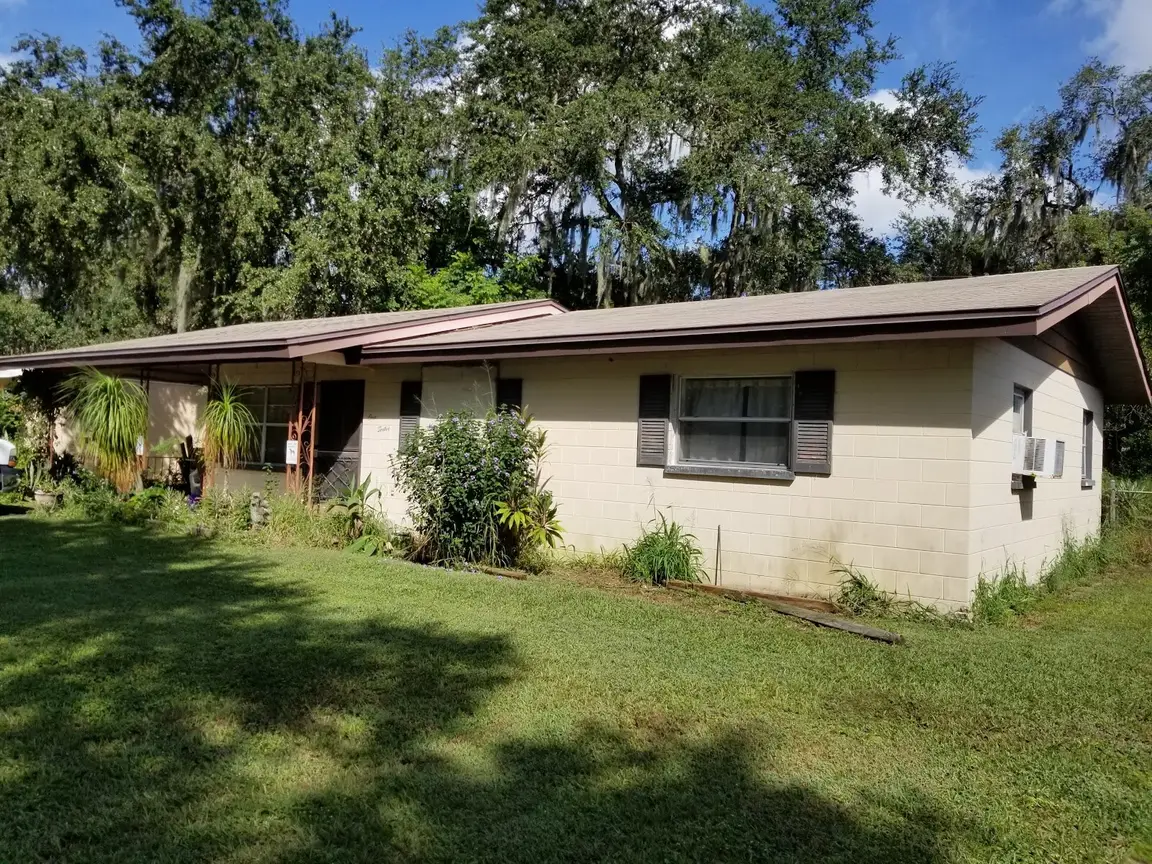
In Florida, a house that needs major work often can’t sell the normal way. It isn’t just the cost of the repairs. An old roof or a failed 4-point inspection can mean a buyer can’t get insurance, and without insurance most buyers can’t get a loan. This page explains why that happens, what your real options are, and how we help owners sell houses that need serious work.
Prefer to talk? Call us at 866-392-2177
Written by Charles M. Contreras, founder of Reliable Home Buyers, Florida real estate license SL3330937. Reliable Home Buyers has made the Inc. 5000 list two years in a row. Updated November 2026.
Short answer: Yes, you can sell a Florida house that needs major repairs without fixing anything. The hard part is usually the buyer’s insurance and loan, not the repairs themselves. A cash buyer doesn’t need a lender or a new insurance policy to close. You still have to tell buyers about known problems that aren’t easy to see.
Key takeaways
- Most buyers need a mortgage, and lenders require insurance. If the house can’t be insured, a financed sale usually falls apart.
- Citizens, Florida’s state-backed insurer, requires a 4-point inspection on homes more than 20 years old.
- Florida law bars insurers from refusing or dropping a policy solely because a roof is under 15 years old. Older roofs can stay insurable if an inspection shows 5+ years of life left.
- FHA appraisal guidelines generally call for a roof with at least two years of life left.
- Selling “as-is” doesn’t remove your duty to disclose known defects that buyers can’t easily see.
- We pay cash, buy without repairs or inspections from you, and cover the closing costs.
On this page: How we help · Why repair houses stall · Problems and how we handle them · Your options · Fix or sell? · Disclosure rules · Common situations · Our process · Real examples · FAQ
How We Help When Your House Needs Major Repairs
We’re not contractors, inspectors, or insurance agents. We’re Florida home buyers who buy houses with big repair problems every month. Here’s what we actually do.
- We don’t need a bank or an insurer to say yes. We pay cash, so there’s no lender appraisal, no lender repair list, and no new insurance policy holding up the closing.
- You don’t need a new 4-point or roof inspection. If you already have one that failed, share it with us. It helps us price the house, but it doesn’t stop the sale.
- We price the repairs in up front. We walk the house once, estimate the work, and tell you which repairs drove our number. No surprise repair requests after the contract is signed.
- We work through permit problems. Open permits or unpermitted work don’t automatically stop us. We work through them with the title company.
- Your insurance was dropped? We can still buy. A canceled or nonrenewed policy doesn’t stop a cash sale to us.
- We cover the closing costs. There are no fees and no commissions. The price we agree on is what you get, minus any mortgage or liens you owe.
- We’ll be honest about fixing first. If a few small repairs and a listing would put more money in your pocket, we’ll tell you.
Why Florida Houses That Need Repairs Stall on the Market
Most buyers pay with a mortgage. Lenders require homeowners insurance, and in Florida, insurers look hard at older homes. That chain is where repair houses get stuck.
- The 4-point inspection. Citizens Property Insurance requires a 4-point inspection on homes more than 20 years old. A licensed inspector checks the roof, electrical, plumbing, and heating and air. Many private insurers ask for one too.
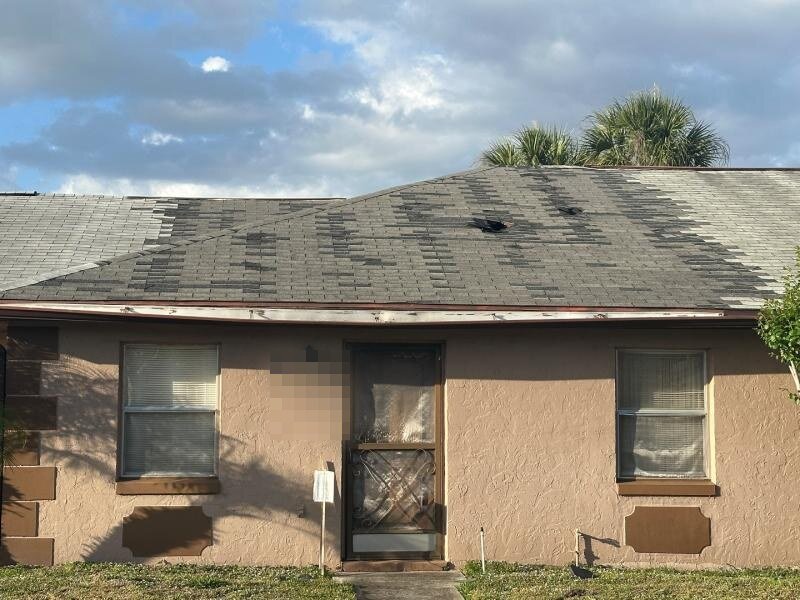
- The roof. Citizens requires proof of at least five years of remaining life on shingle roofs over 25 years old, and on tile or metal roofs over 50. Florida Statute 627.7011 says an insurer can’t refuse or drop a policy solely because a roof is under 15 years old. For older roofs, an inspection showing five or more years of life left protects the policy.
- The lender’s own rules. FHA and VA loans have minimum property standards. FHA appraisal guidelines generally call for a roof with at least two years of life left. Safety issues like exposed wiring or active leaks can also stop a government-backed loan.
- The appraisal. If the house appraises low because of its condition, the buyer may need more cash or walk away.
When any link in that chain breaks, the buyer’s deal falls through. You’re back on the market, often weeks later, with a house that now has a history.
Common Repair Problems and How We Handle Them
| Problem | Why it stalls a normal sale | How we handle it |
|---|---|---|
| Old or leaking roof | Buyers may not get insurance, and FHA buyers may not get a loan. | We buy with the roof as it is and price the replacement into our offer. |
| Failed 4-point inspection | Insurers often won’t write a policy until the problem is fixed. | No new inspection needed. Your failed report just helps us price it. |
| Old electrical panel or wiring | Many insurers won’t cover certain older panels or wiring types. | We factor in the electrical work. You don’t hire an electrician. |
| Old plumbing (like polybutylene pipes) | Insurers often flag it as a leak risk and may refuse coverage. | We price in the repipe and buy the house as it is. |
| Foundation or sinkhole issues | Lenders and insurers may need engineer reports and repair proof. | We review what you have, including any past sinkhole claim, and make an offer. |
| Water damage or mold | Buyers get scared off, and inspections turn up more problems. | We expect it in older Florida homes and include it in our number. |
| Open permits or unpermitted additions | Title and lenders flag them, and closings get delayed. | We work through them with the title company instead of making you fix them first. |
Your Options for Selling a House That Needs Major Repairs
| Option | Good fit if… | Trade-offs |
|---|---|---|
| Fix it, then list it | You have the cash, time, and contractors, and the repairs will raise the price more than they cost. | Upfront cost, permits, delays, and surprise problems. You keep paying the mortgage, taxes, insurance, and utilities the whole time. |
| List it as-is with an agent | The house is in decent shape overall, and buyers can still get insurance and a loan. | Commissions, showings, and financed buyers who may still fail the inspection, insurance, or appraisal. |
| Offer a repair credit | A buyer is interested but wants money off for repairs. | Lenders can limit credits, and the insurance problem may still stop the loan. |
| Sell to us for cash | You want a sure closing without fixing, inspecting, or insuring the house first. | Our offer accounts for the repairs, so it may be less than a fully fixed house would sell for. We’ll show you how we got our number. |
Should You Fix the House Before Selling?
Sometimes fixing first makes sense. Sometimes it just costs you time and money. Ask yourself these questions:
- Will the repair raise the price by more than it costs? Cosmetic fixes like paint and cleaning often pay off. A roof or a repipe often doesn’t come back dollar for dollar.
- Can you pay for it now? Contractors usually want deposits up front, and big jobs can run over budget.
- How long will it take? Permits, contractor schedules, and inspections can add months. You keep paying the bills the whole time.
- What else will they find? Opening walls or tearing off a roof often uncovers more work.
- Can a buyer insure it after you fix it? Fixing one item may not be enough if the 4-point flags others.
For houses that need serious work, the median rehab estimate on homes we’ve signed contracts on since November 2025 is about $55,000. If you’re facing repairs like that, tell us. We’ll be straight with you about whether fixing first makes sense.
Florida Disclosure Rules When You Sell As-Is
Selling as-is means you won’t make repairs. It doesn’t mean you can hide problems.
- Known hidden defects. Under the Florida Supreme Court case Johnson v. Davis (1985), a seller must disclose known problems that materially affect the home’s value and aren’t easy for a buyer to see.
- Sinkhole claims. Under Florida Statute 627.7073, if you were paid on a sinkhole claim, you must tell the buyer before closing and say whether the full payment was used to repair the damage.
- Be upfront with us too. The more we know at the start, the more accurate our offer, and the less chance of changes later.
Trusted resources
- Florida Statute 627.7011: Homeowners policies and roof age
- Florida Statute 627.7073: Sinkhole reports and seller disclosure
- Citizens Property Insurance: Inspection requirements
Common Situations We Help With
- Your insurer dropped you or won’t renew. The roof or the 4-point failed, and now the house is hard to insure and hard to sell.
- A buyer’s loan fell through. The appraisal, inspection, or insurance killed the deal, and you’re back to square one.
- The roof is leaking or near the end of its life. You can’t afford a new roof, and every rain makes it worse.
- It needs a full remodel. Original kitchen and baths, old systems, and floors that need replacing.
- You inherited a house that needs work. See our guide to selling an inherited house in Florida.
- It’s a rental a tenant left in rough shape. See our guide to selling a rental property in Florida.
- You’re behind on payments and can’t afford repairs. Read our Florida foreclosure guide.
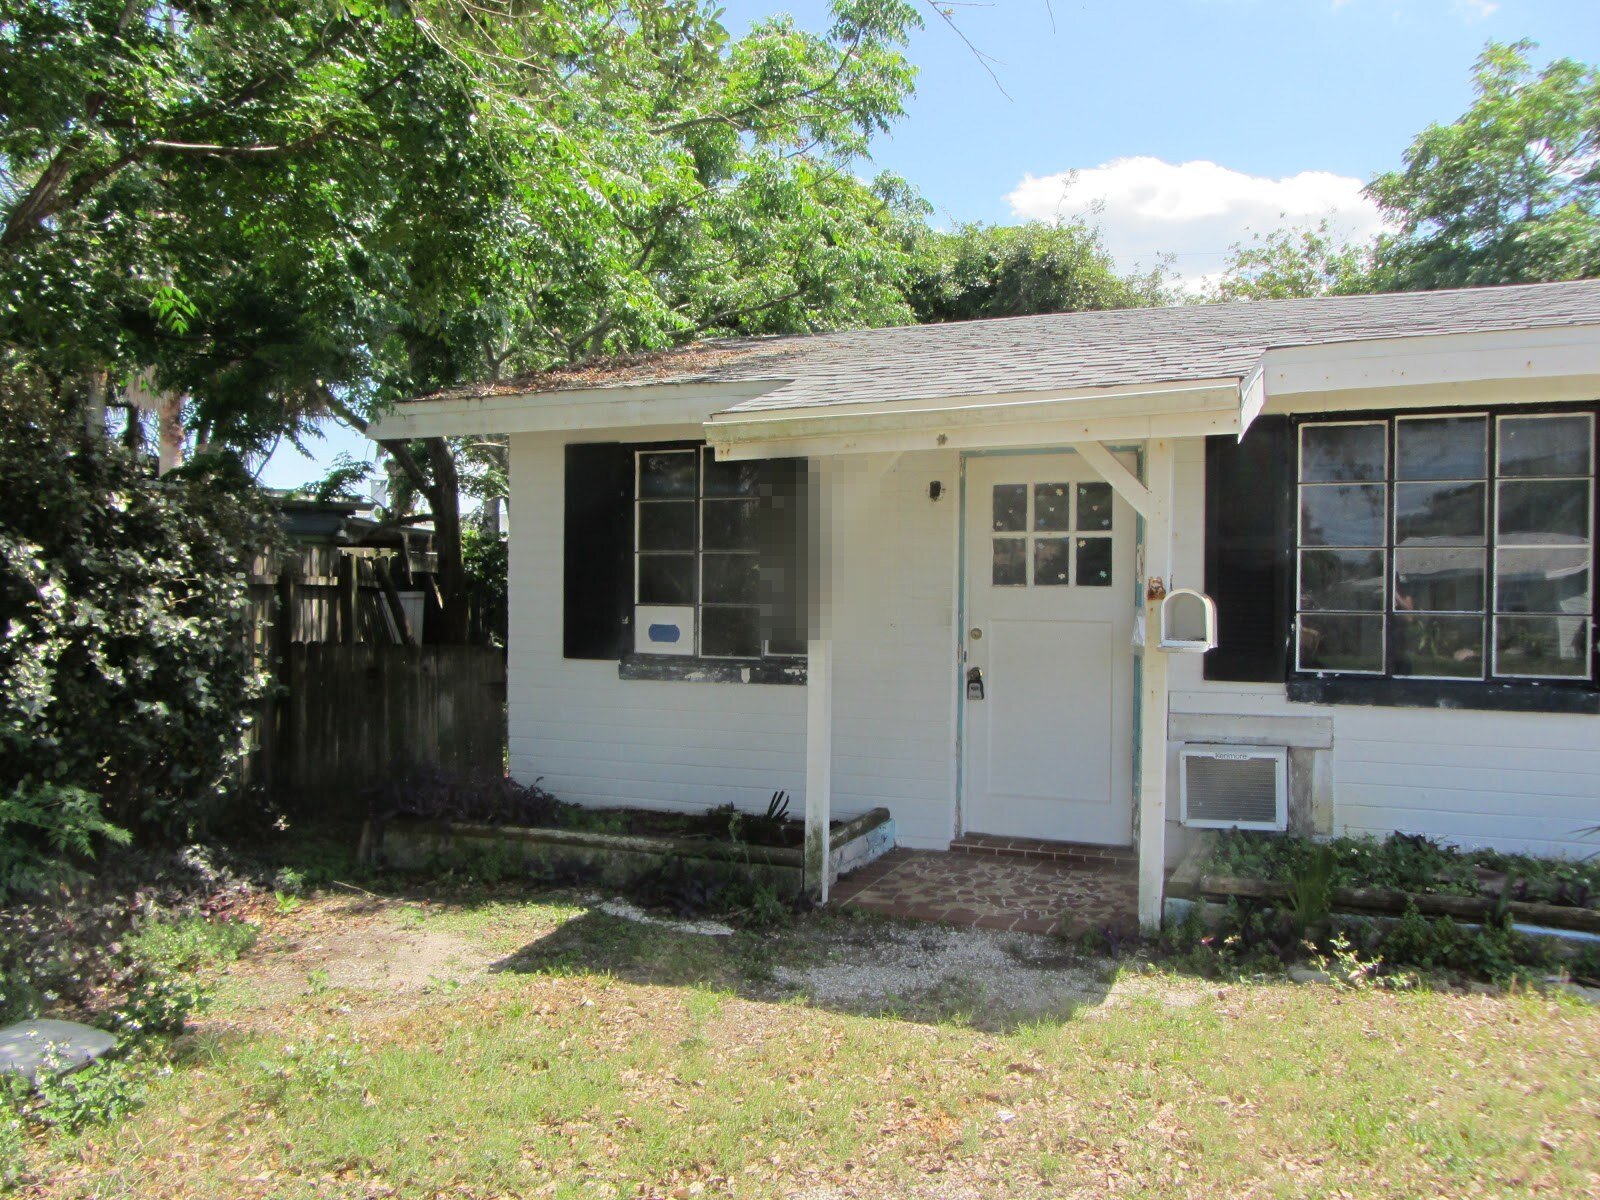
How Selling a House That Needs Repairs to Us Works
- Tell us about the house. Share the address and what you know about the roof, systems, and repairs. Any inspection reports help. Fill out the form or call us.
- Get a fair cash offer. We walk the house once, then give you a written, no-obligation offer and explain the repairs we priced in.
- Close on your timeline. We close at a local title company. We cover the closing costs, and you don’t fix, clean, or inspect anything first.
Real Florida Houses Needing Repairs We’ve Bought
- 1* Virginia Ct, Orange Park. No updates in years, a 15-year-old roof that needed evaluation, and a pool liner to replace. Signed contract September 17, 2026, closed October 9, 2026, just 22 days later.
- 8*** Juniper Rd, Ocala. A house needing more than $100,000 in work. Signed contract August 2, 2026, closed August 24, 2026, just 22 days later.
- 1*** Ashwood Ave, Titusville. Ceiling damage, a full remodel needed, and a water heater to replace. Signed contract May 7, 2026, closed June 4, 2026, less than a month later.
Since November 2025, the median repair estimate on houses we’ve signed contracts on is about $55,000.
Frequently Asked Questions About Selling a House That Needs Repairs in Florida
Can I sell my house in Florida without making repairs?
Yes. You can sell a Florida house as-is without fixing anything. You still need to disclose known problems that buyers can’t easily see. A cash buyer like us doesn’t need you to make repairs, get inspections, or line up insurance.
Can I sell a house with an old roof in Florida?
Yes. An old roof mostly hurts financed buyers, because they need insurance and their lender’s approval. Citizens requires proof of at least five years of remaining life on shingle roofs over 25 years old. We pay cash, so the roof’s age doesn’t stop us from buying.
What happens if my house fails a 4-point inspection?
A failed 4-point inspection can make it hard for a buyer to get insurance, which can stop their loan. You can fix the items and re-inspect, offer a credit, or sell to a cash buyer who doesn’t need a new policy to close.
Will my insurance company drop me because my roof is old?
Under Florida Statute 627.7011, an insurer can’t refuse or drop a policy solely because the roof is under 15 years old. For older roofs, you can get an inspection. If it shows five or more years of life left, the insurer can’t refuse coverage solely because of the roof’s age.
Do I have to disclose problems if I sell as-is in Florida?
Yes. Florida sellers must disclose known defects that materially affect the home’s value and aren’t easy to see. If you were paid on a sinkhole claim, you must also tell the buyer whether the money was used for repairs. Talk to a Florida real estate attorney if you’re unsure.
Can I sell a house with open permits or unpermitted work?
Usually, yes. The title search may flag open permits, and some buyers’ lenders won’t close with them. We work through permit issues with the title company instead of making you fix everything first.
Should I fix my house before selling it?
It depends on the repair. Cleaning and paint often pay off. Big jobs like a roof, repipe, or full remodel often don’t return what they cost, and they take time. Tell us about your house, and we’ll be honest about whether fixing first makes sense.
Do I pay any fees or commissions?
No. There are no fees and no commissions when you sell to us, and we cover the closing costs.
Ready to Sell Without Fixing It First?
Tell us about your house, or call us at 866-392-2177 We’ll look at your situation, give you a fair no-obligation cash offer, and tell you honestly whether another option might be better for you.
We buy houses that need repairs across Florida, including: Tampa · Orlando · Jacksonville · Melbourne · Daytona Beach · Sarasota · West Palm Beach · Fort Myers · Ocala · Pensacola
More help: Selling a house that needs major repairs in Sanford · Selling a distressed property without repairs · Selling a rental property in Florida · Selling an inherited house in Florida · Stopping foreclosure in Florida
Disclaimer: This page is general information, not legal, insurance, or construction advice. Reliable Home Buyers is a home buying company, not a law firm, insurance agency, contractor, or inspector. Insurance rules change, so check with your agent or insurer about your policy.